The Secondary Markets: Broker and Dealer Markets serve as the cornerstone of global financial liquidity, facilitating the continuous buying and selling of previously issued financial assets among institutional and retail investors.
By providing price discovery, market efficiency, and immediate execution, these secondary trading mechanisms lower the cost of capital for corporate issuers and provide investors with essential risk management tools across national exchanges, regional exchanges, NASDAQ, and over-the-counter platforms.
Introduction to Secondary Financial Markets
Financial markets are divided into primary and secondary segments. While primary markets facilitate initial capital creation—enabling corporations, sovereign governments, and municipalities to raise fresh funds via Initial Public Offerings (IPOs) or bond underwritings—secondary markets exist to facilitate trading in pre-existing financial instruments. Once an asset is issued, its ongoing liquidity and market valuation depend entirely on secondary market architecture.
Without robust secondary markets, primary market capital raising would become prohibitively expensive. Investors would demand steep illiquidity premiums to buy securities if they lacked a reliable, standardized mechanism to sell those holdings later. The global equity market capitalization has expanded to over USD75.3 trillion, underscoring the vital role secondary venues play in mobilizing institutional capital worldwide.
Secondary financial infrastructure is broadly bifurcated into two foundational execution archetypes: broker markets (order-driven auction structures) and dealer markets (quote-driven, decentralized frameworks). Understanding the distinct operating mechanics, regulatory standards, and technology stacks of national exchanges, regional exchanges, NASDAQ, and over-the-counter (OTC) venues is essential for corporate financial officers, institutional portfolio managers, and regulatory policymakers.
Broker Markets vs. Dealer Markets: Fundamental Mechanics
The primary distinction between secondary market structures lies in how trades are routed, executed, and settled, as well as the principal role assumed by market intermediaries.
The Structural Dynamics of Broker Markets
A broker market is an order-driven, centralized venue where buyers and sellers meet directly or through designated representatives on an exchange floor or electronic matching engine.
- Role of the Broker: Brokers act strictly as agents on behalf of their clients. They do not own the securities being traded, nor do they commit firm capital to take asset positions.
- Revenue Model: Brokers earn compensation through transaction commissions, routing fees, or agency markups.
- Price Discovery: Executions occur when a buy order and a sell order intersect at a mutually agreed price. The market functions as a continuous double auction, matching the highest bid price with the lowest ask price.
- Risk Exposure: Because brokers do not hold inventory, they bear zero inventory price risk. However, they must manage counterparty credit risk and operational trade processing risk.
The Operational Dynamics of Dealer Markets
A dealer market is a quote-driven framework in which independent dealers maintain inventory and actively buy and sell securities for their own proprietary accounts.
- Role of the Dealer: Dealers act as principals in every trade. When an investor places an order in a dealer market, the investor trades directly against the dealer’s portfolio rather than matching directly with another end investor.
- Revenue Model: Dealers generate profits primarily through the bid-ask spread—the difference between the lower price at which they purchase a security (bid) and the higher price at which they sell it (ask).
- Inventory Risk: Dealers take on inventory price risk. If a dealer holds substantial equity shares and market prices drop sharply before those shares can be offloaded, the dealer absorbs the loss.
- Liquidity Provision: Dealers function as market makers. By committing balance sheet capital to quote two-sided markets, dealers provide immediate liquidity even when an end buyer or seller is not immediately available.
| Structural Attribute | Broker Market (Order-Driven) | Dealer Market (Quote-Driven) |
| Intermediary Role | Agent (acts on behalf of client) | Principal (trades from own inventory) |
| Execution Mechanism | Centralized Order Matching / Continuous Auction | Decentralized Dealer Quote Comparison |
| Primary Income Source | Transaction Commissions & Fees | Bid-Ask Spread (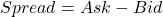 |
| Inventory Risk | None (does not hold asset inventory) | Significant (holds positions on balance sheet) |
| Price Determination | Direct matching of buyer bid and seller ask | Dealer quote publication & negotiation |
| Primary Examples | New York Stock Exchange (NYSE), Tokyo Stock Exchange | NASDAQ (historical model), OTC Markets Group |

National Exchanges: High-Volume Auction Hubs
National securities exchanges represent the most formalized, tightly regulated segment of secondary trading. To qualify for listing on a national exchange, corporations must satisfy rigorous quantitative thresholds (such as minimum market capitalization, annual net income, and public float balance) alongside corporate governance standards.
The New York Stock Exchange Model
The New York Stock Exchange, operated by Intercontinental Exchange, stands as the world’s largest equity exchange by market capitalization. The NYSE historically operated as a physical floor-based broker market, relying on an auction structure directed by Designated Market Makers (DMMs).
Today, national venues operate as hybrid environments, blending high-speed algorithmic execution engines with human floor oversight:
- Designated Market Makers (DMMs): DMMs manage the continuous order book for assigned listed securities. Unlike standard dealers, DMMs possess affirmative obligations to maintain fair and orderly markets, stepping in with proprietary capital to buy or sell during supply-demand imbalances.
- Listing Standards: Major global enterprises such as Apple Inc. and Shell plc choose national exchange listings to maximize global visibility, maintain prestige, and attract multi-billion-dollar institutional allocations.
- Consensus Pricing: National exchanges offer centralized market data consolidation, displaying transparent consolidated order books that establish benchmark prices across world financial markets.
Regional Exchanges: Specialized Liquidity and Local Capital Access
Regional stock exchanges originally formed outside primary financial centers to facilitate capital formation for local enterprises that did not meet national listing criteria.
Evolution and Modern Institutional Integration
Historically prominent regional venues—such as the Chicago Stock Exchange (now NYSE Chicago), the Boston Stock Exchange, and the Philadelphia Stock Exchange—played pivotal roles in expanding equity access across North America. Over recent decades, regional exchanges have undergone technological integration and corporate consolidation.
Regional venues currently fulfill several key strategic functions:
- Dual Listing and Order Routing: Smaller regional exchanges allow secondary trading of national securities, offering alternative routing pathways for institutional trading desks seeking price improvement or specialized order types.
- Niche Product Focus: Many regional exchanges transitioned into specialized asset hubs. For instance, the Philadelphia venue evolved into a primary options execution market before being acquired by Nasdaq, Inc..
- National Market System Integration: Under U.S. Regulation NMS (specifically Rule 611, known as the Order Protection Rule), top-of-book quotes across all registered regional and national exchanges must be linked electronically. If a regional venue offers the National Best Bid or Offer (NBBO), orders across the country must route to that venue, preventing trade-throughs at inferior prices.
NASDAQ: The Evolution of Screen-Based Electronic Dealer Markets
Created in 1971 by the National Association of Securities Dealers (NASD), NASDAQ originally operated as an automated quotation system (National Association of Securities Dealers Automated Quotations) that displayed dealer price quotes across a computer network. Over time, NASDAQ transformed into a full-fledged registered national securities exchange, completely changing global equity execution mechanics.
Market Structure and Multi-Dealer Competition
Unlike traditional single-specialist auction floors, NASDAQ pioneered an electronic, competing dealer model:
- Multiple Market Makers: For a given NASDAQ-listed enterprise, dozens of competing dealer firms post firm bid and ask prices simultaneously. This competition compresses bid-ask spreads, directly benefiting retail and institutional traders.
- Screen-Based Execution: Automated execution networks automatically match incoming electronic orders against the best available dealer quotes across the network, eliminating physical trading floors.
- Tiered Market Structure: NASDAQ organizes listings into structured market tiers based on market capitalization, liquidity, and corporate governance requirements:
- Nasdaq Global Select Market: Reserved for the largest, most liquid global corporate leaders, including technological blue-chips like Microsoft Corporation.
- Nasdaq Global Market: Geared toward mid-cap international enterprises with substantial institutional backing.
- Nasdaq Capital Market: Designed for early-stage and growth-oriented firms seeking initial equity capital.
NASDAQ’s electronic architecture demonstrated that dealer markets could handle immense transaction volumes efficiently, leading global issuers like Samsung Electronics and Toyota Motor Corporation to utilize screen-based ADR trading to tap U.S. dollar capital pools.
Over-the-Counter (OTC) Markets and Alternative Trading Systems
The Over-the-Counter (OTC) market encompasses trading in securities that are not listed on formal national or regional stock exchanges. The OTC market is a decentralized, network-driven dealer market where securities dealers negotiate trades directly via telephone, messaging platforms, and electronic proprietary networks.
The Modern OTC Market Structure
Historically associated with paper-based “Pink Sheets” and manual quotation bulletin boards (OTCBB), the OTC equity market has undergone modernization led by electronic platform operators such as OTC Markets Group Inc.. In 2025, annual trading volume across OTC Markets reached USD609 billion, driven by expanding international cross-border liquidity and growth in cross-traded European issuers.
OTC equity trading is organized into distinct market tiers based on corporate disclosure standards and financial integrity:
- OTCQX (The Best Market): The top tier for established international and domestic companies. It requires strict financial reporting, audited accounts, and corporate governance checks, while bypassing duplicate SEC registration burdens. Established global issuers like LVMH Moët Hennessy Louis Vuitton trade their cross-border ADRs on OTCQX to provide seamless liquid execution for North American investors.
- OTCQB (The Venture Market): Aimed at early-stage and venture-focused growth companies that report financial results to domestic or international regulators but do not yet satisfy national exchange capital requirements.
- Pink Open Market: A trading venue for speculative, distressed, or unlisted small-cap issuers with varying levels of disclosure requirement enforcement.
Beyond equities, major global financial markets—including the USD130+ trillion global fixed-income (bond) market, foreign exchange (FX) market, and complex bilateral derivatives—operate almost exclusively as OTC dealer markets. In these venues, institutional dealers commit balance sheet capital to quote customized credit, rate, and currency trades to corporate treasurers and pension funds.
Comparative Overview of Secondary Market Architecture
To synthesize how secondary trading platforms compare across operational metrics, the table below outlines the core attributes of each primary execution venue.
| Feature / Metric | National Exchanges (e.g., NYSE) | Regional Exchanges | NASDAQ Market Tiers | Over-the-Counter (OTC) Markets |
| Execution Archetype | Hybrid Auction / Order-Driven | Electronic Order Matching | Competing Electronic Dealer | Decentralized Inter-Dealer |
| Primary Intermediary | Designated Market Maker (DMM) / Agency Broker | Regional Broker / System Router | Competing Market Makers | Individual Securities Dealers |
| Market Transparency | Highest (Real-time public tape) | High (Integrated via Reg NMS) | Highest (Level 1, 2, & 3 Data) | Variable (Tier-dependent: OTCQX high, Pink lower) |
| Listing Standards | Most Stringent (High revenue & float) | Moderate / Specialization | Stringent to Moderate | Ranges from Standardized (OTCQX) to Minimal |
| Asset Diversity | Mega & Large-Cap Equities, ETFs | Equities, Options, Niche Derivatives | Tech, Growth, Mid-to-Large Equities | Cross-Border ADRs, Fixed Income, Foreign Exchange |
| Trading Volume Share | Dominant Primary Listing Volume | Order Execution Routing Share | Dominant Tech & Growth Volume | Niche Equity / Dominant Debt & FX Volume |
Market Microstructure, Regulatory Dynamics, and Technological Fusion
Modern secondary markets have moved beyond strict historical definitions. The traditional line separating broker auction floors from electronic dealer networks has blurred, driven by technological innovations and regulatory reforms.
Regulation NMS and Market Fragmentation
In the United States, the implementation of SEC Regulation NMS transformed market microstructure. By requiring market centers to route customer orders to whichever platform posts the best visible price across the national market system, Reg NMS fostered intense competition among execution venues.
However, this regulation also introduced structural fragmentation:
- Dark Pools & Internalization: Broker-dealers often execute orders internally or route retail orders to off-exchange alternative trading systems (ATSs) or dark pools. Dark pools allow institutional investors to trade multi-million-dollar blocks without signaling order intent to public markets, minimizing price impact.
- High-Frequency Trading (HFT): Advanced automated trading firms utilize high-frequency algorithms to capitalize on microsecond pricing differentials across fragmented national, regional, and electronic dealer venues. HFT firms frequently step into dealer roles, providing electronic liquidity without carrying overnight inventory.
The Synthesis of Broker and Dealer Functions
Today, major global financial institutions routinely operate integrated broker-dealer divisions. A single financial firm may act as an agency broker on one trade (matching an institutional buy order with a sell order on the NYSE) while acting as a principal dealer on another (selling corporate bonds or tech shares directly out of its internal inventory).
This integration maximizes execution efficiency, allowing market participants to source liquidity across public national exchanges, specialized regional networks, competing NASDAQ dealer screens, and deep OTC institutional pools.
Strategic Implications for Corporate Leaders and Investors
Understanding secondary market design is vital for financial executives, institutional investors, and economic advisors:
- Optimizing Capital Structure: Corporate chief financial officers must choose listing venues strategically. A primary national listing on NYSE or NASDAQ signals regulatory compliance, enhancing institutional index inclusion (such as the S&P 500 or Nasdaq-100). Simultaneously, leveraging OTCQX cross-trading can unlock global investor bases without adding redundant administrative overhead.
- Minimizing Transaction Costs: Institutional portfolio managers must analyze market microstructure—evaluating bid-ask spreads, venue latency, and market depth—to minimize price slippage when rebalancing multi-billion-dollar portfolios.
- Ensuring Systemic Stability: Regulators and government advisors must continuously update market structure policies to balance rapid electronic execution with financial stability, ensuring that both order-driven broker markets and quote-driven dealer networks maintain resilient liquidity during market stress.
As global capital markets continue to evolve, the integration of electronic order matching, algorithmic market-making, and regulatory transparency ensures that secondary broker and dealer markets will remain central engines of international investment, enterprise expansion, and economic growth.

