Understanding trading costs and electronic markets is fundamental for institutional investors, corporate executives, portfolio managers, and regulatory policymakers seeking to optimize investment returns and navigate modern financial market infrastructure.
Transaction costs represent a persistent friction that directly erodes net portfolio performance, while the evolution of electronic trading venues fundamentally alters how financial orders are routed, matched, and executed globally.
This article delivers a rigorous examination of the components of execution costs, methods for calculating transaction cost benchmarks—including effective spreads, Volume-Weighted Average Price (VWAP), and Implementation Shortfall—the structural drivers of market fragmentation, taxonomy of electronic traders, competitive mechanics of low-latency trading, regulatory risk mitigation frameworks, and real-time market surveillance techniques.
Introduction to Trading Costs and Electronic Markets
In global equity, fixed income, foreign exchange, and derivative markets, gross investment returns rarely translate directly into net realized returns. The gap between paper performance and actual portfolio performance is driven by transaction costs incurred during trade execution. Over long investment horizons, even small execution inefficiencies can compound into substantial drag on assets under management.
At the same time, global capital markets have transitioned from manual, floor-based open outcry trading to highly automated, algorithmic electronic trading systems. Venues operated by exchange groups such as Nasdaq, Intercontinental Exchange (owner of the New York Stock Exchange), London Stock Exchange Group, and Euronext process billions of orders daily with microsecond execution latencies. Understanding the interplay between trading costs and electronic markets is therefore vital for institutional asset managers like BlackRock and quantitative liquidity providers like Citadel Securities.
Components of Execution Costs: Explicit vs. Implicit
Total transaction costs incurred when executing trades are broadly divided into explicit costs and implicit costs. While explicit costs are transparent and invoiced directly, implicit costs are embedded within price movements and order book dynamics, frequently representing the larger portion of total execution drag.
                          ┌────────────────────────────────────────────────────────┐
                          │                 Total Execution Costs                  │
                          └───────────────────────────┬────────────────────────────┘
                                                      │
                       ┌──────────────────────────────┴──────────────────────────────┐
                       │                                                             │
        ┌──────────────┴──────────────┐                               ┌──────────────┴──────────────┐
        │       Explicit Costs        │                               │       Implicit Costs        │
        └──────────────┬──────────────┘                               └──────────────┬──────────────┘
                       │                                                             │
  ┌────────────────────┼────────────────────┐                   ┌────────────────────┼────────────────────┐
  │                    │                    │                   │                    │                    │
Brokerage           Exchange &          Financial          Bid-Ask              Market               Delay &
Commissions         Clearing Fees       Taxes / Stamps     Spread               Impact               Opportunity Cost
Explicit Costs
Explicit costs are direct, contractually defined payments made to intermediaries and market infrastructure providers to facilitate a trade. Key components include:
- Brokerage Commissions: Fees paid to sell-side brokers (such as Goldman Sachs or Morgan Stanley) for order routing, execution management, and clearing services.
- Exchange and Trading Venue Fees: Transaction assessments levied by primary exchanges and alternative trading systems for order matching and access.
- Clearing and Settlement Charges: Operational fees assessed by central clearing houses (e.g., DTCC in the United States or Euroclear in Europe) to settle securities transactions.
- Financial Transaction Taxes and Stamp Duties: Government-imposed levies, such as the UK Stamp Duty Reserve Tax or the French Financial Transaction Tax, charged on transactions in registered securities.
Implicit Costs
Implicit costs arise from market microstructure dynamics and liquidity constraints. Because they cannot be identified on a simple broker invoice, measuring implicit costs requires quantitative benchmarks.
- Bid-Ask Spread: The baseline cost of accessing immediate liquidity. Buyers pay the higher ask price (


- Market Impact (Price Impact): The adverse price movement caused by the execution of a large order. As an institutional order consumes available liquidity at the top of the order book and pushes deeper into market depth, successive fills occur at progressively worse prices.
- Delay Cost (Slippage): The price change that occurs between the moment an investment decision is finalized and the time the order is physically submitted to the market.
- Opportunity Cost (Unexecuted Order Cost): The cost of adverse price movement on unfilled portions of an order. If a stock price rallies significantly while a buy order remains partially executed, the unexecuted shares represent lost investment return.

Calculating and Interpreting Effective Spreads and VWAP Benchmarks
Transaction Cost Analysis (TCA) relies on standardized metrics to evaluate trade execution quality against prevailing market benchmarks. Two foundational metrics are the Effective Spread and the Volume-Weighted Average Price (VWAP).
Effective Spread Calculation and Interpretation
While the quoted bid-ask spread represents the static difference between prevailing quotes at a given moment, trades often execute inside or outside those quotes. The effective spread measures the actual round-trip cost incurred by a trader relative to the midpoint of the bid-ask quote at the time of order arrival.
For a buy order executing at price 

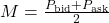


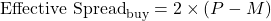

For a sell order executing at price


To allow comparisons across securities of different price levels, the relative effective spread is expressed as a percentage or in basis points (bps):
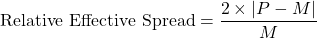

An effective spread smaller than the quoted spread indicates price improvement (e.g., execution within the spread on an internalizing venue or dark pool). An effective spread greater than the quoted spread indicates market impact due to order size exceeding top-of-book depth.
Volume-Weighted Average Price (VWAP) Transaction Cost Analysis
VWAP serves as a primary benchmark for institutional traders executing orders over an extended trading window. VWAP reflects the average price at which a security traded throughout the day, weighted by trading volume at each price level:
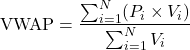

Where 


The VWAP transaction cost estimate measures how effectively an execution algorithm or trade desk completed an order relative to the market average:
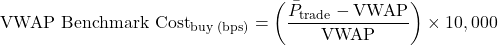

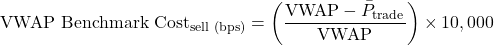

Where 

Comparative Benchmark Calculations
The following table presents empirical trade execution metrics for an institutional buy order of 50,000 shares in a large-cap equity security.
| Parameter / Metric | Market Quote / Trade Data | Formula / Calculation | Value (USD) / Basis Points |
| Prevailing Bid Price ( | USD100.00 | Quote | USD100.00 |
| Prevailing Ask Price ( | USD100.10 | Quote | USD100.10 |
| Quote Midpoint ( | USD100.05 | 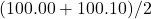 | USD100.05 |
| Quoted Spread | USD0.10 | 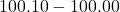 | USD0.10 (10.0 bps) |
| Actual Fill Price ( | USD100.08 | Executed price | USD100.08 |
| Effective Spread (Absolute) | USD0.06 | 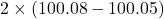 | USD0.06 |
| Relative Effective Spread | 5.997 bps | 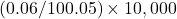 | ~6.00 bps |
| Full-Day Market VWAP | USD100.02 | Volume-weighted market total | USD100.02 |
| VWAP Execution Cost | +5.999 bps | 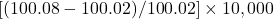 | +6.00 bps |


The Implementation Shortfall Approach to Transaction Cost Measurement
First introduced by André Perold, Implementation Shortfall (IS) is a holistic transaction cost measurement methodology that compares the actual performance of an executed portfolio against a hypothetical “paper” portfolio where trades execute instantaneously at the decision price without costs or market impact.
Conceptual Framework of Implementation Shortfall
Traditional post-trade benchmarks (such as VWAP) evaluate executions only against market activity during the trade horizon. They fail to capture the opportunity costs of unfilled orders or the delay costs incurred before order entry. Implementation Shortfall resolves this by accounting for all frictions from the precise moment an investment manager makes the asset allocation decision.
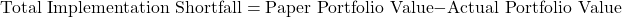

Decomposition of Implementation Shortfall Components
To provide actionable insights for portfolio management, Implementation Shortfall is decomposed into four granular sub-components:
- Explicit Costs (

- Delay Cost (Slippage): Cost resulting from price movements between decision time (


- Realized Price Impact (Execution Drag): Cost incurred when fills execute at prices (

- Opportunity Cost (Missed Trade Drag): Cost of unexecuted shares (


For a buy order of target quantity 

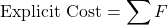

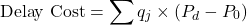

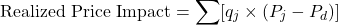

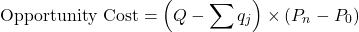

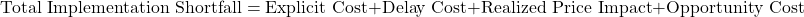

Comprehensive Numerical Case Study of Implementation Shortfall
Consider an institutional portfolio manager at J.P. Morgan Asset Management who decides to buy 100,000 shares of a technology stock.
- Decision Price (
- Arrival Price (
- Trade Execution Fills:
- Fill 1 (


- Fill 2 (


- Fill 1 (
- Executed Quantity: 80,000 shares.
- Unexecuted Quantity: 20,000 shares.
- End-of-Day Benchmark Closing Price (
- Total Explicit Fees (


| Shortfall Component | Mathematical Formula | Detailed Calculation | Total Amount (USD) | Cost in Basis Points |
| Explicit Costs |  | Flat commissions and clearing fees | USD2,000 | 4.00 bps |
| Delay Cost | 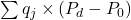 | 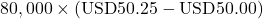 | USD20,000 | 40.00 bps |
| Realized Price Impact | 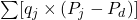 | 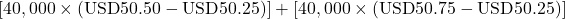 | USD30,000 | 60.00 bps |
| Opportunity Cost | 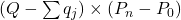 | 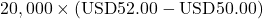 | USD40,000 | 80.00 bps |
| Total Shortfall | Sum of all 4 components | 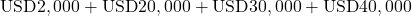 | USD92,000 | 184.00 bps |


Note: Basis point values are calculated relative to the target paper investment value of USD5,000,000 (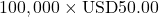

The master formula verifies this calculation:
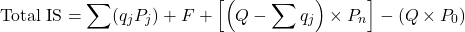

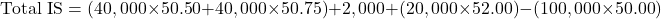

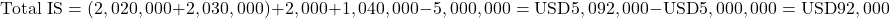

Drivers of Electronic Trading Systems Development
The transition from physical trading pits to automated electronic execution systems has been accelerated by structural market shifts:
- Cost Reduction and Operational Scalability: Electronic platforms eliminate manual floor processing, reducing processing costs and operating risks.
- Execution Speed and Processing Capacity: Computer networks match orders within microseconds, handling transaction flows that would collapse manual infrastructure.
- Regulatory Mandates: Major regulatory overhauls—including Regulation NMS in the United States and MiFID II in the European Union—mandated transparent order routing, best execution compliance, and consolidated pre- and post-trade tape reporting.
- Growth of Quantitative and Passive Asset Management: The expansion of index-tracking mutual funds, ETFs managed by firms such as Vanguard and BlackRock, and quantitative hedge funds created demand for automated order execution algorithms.
- Democratization of Global Market Access: Advanced Application Programming Interfaces (APIs) allow market participants worldwide to deploy capital across multi-asset venues seamlessly.
Market Fragmentation and Liquidity Aggregation
Market fragmentation occurs when trading in a single financial instrument is split across multiple competing venues rather than concentrated on a single centralized exchange.
                              ┌─────────────────────────────────────────┐
                              │            Parent Order Flow            │
                              └────────────────────┬────────────────────┘
                                                   │
                                      ┌────────────┴────────────┐
                                      │ Smart Order Router (SOR)│
                                      └────────────┬────────────┘
                                                   │
        ┌──────────────────────────────┬───────────┴──────────────┬──────────────────────────────┐
        │                              │                          │                              │
┌───────┴────────┐             ┌───────┴────────┐         ┌───────┴────────┐             ┌───────┴────────┐
│ Lit Exchange A │             │ Lit Exchange B │         │  Dark Pool X   │             │ Internalizer Z │
│ (e.g., NASDAQ) │             │  (e.g., NYSE)  │         │  (ATS Venue)   │             │ (Market Maker) │
└────────────────┘             └────────────────┘         └────────────────┘             └────────────────┘
Lit Exchanges vs. Dark Pools and Alternative Trading Systems
Modern liquidity is distributed across distinct operational venues:
- Lit Exchanges: Regulated public venues (e.g., Nasdaq, NYSE) that display pre-trade bid and ask quotes publicly in a Central Limit Order Book (CLOB). Lit venues offer price discovery but expose institutional orders to signaling risk.
- Dark Pools (Alternative Trading Systems / Multilateral Trading Facilities): Non-displayed liquidity venues operated by independent brokers or exchanges (e.g., UBS PIN, Goldman Sachs Sigma X). Pre-trade quotes are hidden; trades execute at the midpoint of the prevailing lit market bid-ask spread. Dark pools minimize market impact for large blocks, but increase execution uncertainty.
- Internalizers and Wholesale Market Makers: Off-exchange firms (such as Citadel Securities or Virtu Financial) that execute retail order flow directly against their proprietary inventory.
While market fragmentation fosters fee competition and exchange innovation, it dilutes order book depth across individual venues, increasing search costs and liquidity isolation.
Smart Order Routing (SOR) Technology
To navigate fragmentation, sell-side brokers and institutional buy-side firms utilize Smart Order Routing (SOR) algorithms. SOR engines continuously monitor real-time market data feeds across lit and dark execution venues. When an order arrives, the SOR splits and routes sub-orders to the venues offering the highest probability of fill, lowest total execution cost, and best net price execution.
Types and Taxonomy of Electronic Traders
The electronic trading ecosystem comprises diverse participants differentiated by investment horizon, trading frequency, inventory holding period, and technology infrastructure.
| Electronic Trader Type | Capital Source / Business Model | Primary Execution Strategy | Average Holding Period | Infrastructure & Latency |
| High-Frequency Market Makers | Proprietary capital (Citadel Securities, Virtu Financial) | Continuous two-sided quote provision, capturing bid-ask spreads | Milliseconds to seconds (Zero overnight risk) | Ultra-low latency, colocation, microwave links, FPGAs |
| Statistical Arbitrage HFTs | Proprietary quantitative firms | Cross-asset/cross-venue price gap exploitation, mean reversion | Seconds to minutes | Co-located servers, sub-microsecond processing |
| Agency Brokers | Client fee model (Goldman Sachs, Morgan Stanley) | Algorithmic execution on behalf of institutional clients | Non-proprietary agency routing | Low latency SOR, API integration, dark aggregators |
| Quantitative Hedge Funds | Institutional investor capital (Two Sigma, Renaissance) | Automated signal processing, predictive trend and momentum execution | Hours to weeks | High-performance computing, medium latency |
| Passive Index Asset Managers | Client AUM management (BlackRock, Vanguard) | Minimize tracking error, scheduled execution (TWAP/VWAP/MOC) | Months to years | Low-cost infrastructure, execution algos |
Characteristics and Strategic Uses of Electronic Trading Systems
Electronic trading systems incorporate specialized technology architectures designed to optimize transaction flows:
- Direct Market Access (DMA): Enables buy-side institutions to route orders directly to an exchange order book using broker infrastructure without manual intervention.
- Sponsored Access: Grants traders direct exchange access using a broker’s clearing identifier, bypassing the broker’s infrastructure entirely. Unfiltered sponsored access is restricted due to risk management concerns.
- Central Limit Order Books (CLOB): Continuous double-auction engines that match buy and sell orders based on price-time priority.
Execution Algorithm Strategies
Institutional market participants utilize algorithmic trade execution to break large parent orders into smaller child orders over time, mitigating market impact:
- Volume-Weighted Average Price (VWAP) Algos: Slice orders dynamically based on historical intraday volume profiles, participating heavily during open and close periods.
- Time-Weighted Average Price (TWAP) Algos: Release equal tranches of shares at fixed time intervals throughout the trading session, regardless of market volume.
- Percent of Volume (POV) Algos: Target a constant participation rate (e.g., 10% of total market volume). If market volume spikes, the algo accelerates execution; if volume dries up, execution slows.
- Implementation Shortfall (IS) Algos: Dynamically balance market impact cost against market risk (alpha decay). If prices move adversely, the algo aggressively executes shares to minimize delay cost.
Comparative Advantages of Low-Latency Traders
Low-latency market participants invest heavily in physical and software infrastructure to operate at sub-microsecond timeframes.
┌─────────────────────────────────────────────────────────────────────────────────┐
│                    Low-Latency Technological Stack                              │
├─────────────────────────────────────────────────────────────────────────────────┤
│  Colocation Facilities    ──► Server racks physically inside exchange center    │
│  Custom Hardware          ──► FPGA & ASIC chip integration for zero-OS parsing │
│  Direct Market Feeds      ──► Binary protocol connections (ITCH/OUCH)           │
│  Microwave Networks       ──► Line-of-sight wireless infrastructure between cities│
└─────────────────────────────────────────────────────────────────────────────────┘
Key technological advantages include:
- Colocation Facilities: Renting server space within the exchange data center (e.g., Equinix NY4 in Secaucus, New Jersey, or LD4 in Slough, United Kingdom). This reduces fiber-optic propagation delays to sub-microsecond levels.
- Direct Market Data Feeds: Bypassing consolidated feeds (such as the US Securities Information Processor / SIP) to subscribe directly to exchange binary feeds (e.g., Nasdaq ITCH/OUCH protocols), gaining real-time order book visibility milliseconds before standard market participants.
- Hardware Acceleration: Utilizing Field-Programmable Gate Arrays (FPGAs) and Application-Specific Integrated Circuits (ASICs) to execute trading logic directly on network interface cards, bypassing operating system overhead.
- Microwave Wireless Networks: Constructing line-of-sight microwave communications towers between key financial hubs (such as Chicago and New Jersey) to transmit market data faster than speed-of-light propagation through glass fiber.
Low-latency firms leverage these technologies to capture bid-ask spreads cleanly, update quotes ahead of adverse market movements, and perform cross-venue price arbitrage.
Risks of Electronic Trading and Regulatory Oversight
While electronic markets increase liquidity and lower explicit trading fees, they introduce operational and systemic risks.
Systemic Risks and Operational Failures
- Flash Crashes: Cascading price declines triggered when automated algorithms simultaneously withdraw liquidity or enter feedback loops (e.g., the US Flash Crash of May 6, 2010, where the Dow Jones Industrial Average fell ~1,000 points in minutes).
- Runaway Algorithms and Software Bugs: Faulty algorithm deployments that enter erroneous orders at high speeds. In August 2012, Knight Capital Group incurred a USD440,000,000 loss in 45 minutes due to an uncalibrated order router code deployment.
- System Outages: Hardware failures or cyber disruptions affecting major exchanges, halting regional price discovery.
Regulatory Mitigation Mechanisms
Regulators globally have instituted operational safeguards to preserve market integrity:
- Limit-Up/Limit-Down (LULD) Bands and Market-Wide Circuit Breakers: Mandatory trading pauses triggered if individual stock prices move outside dynamic price bands (e.g., +/- 5% or 10%), or if benchmark indexes decline significantly (e.g., 7%, 13%, or 20% drops in the S&P 500).
- Pre-Trade Risk Controls (SEC Rule 15c3-5): Mandatory pre-trade credit checks and order-size filters imposed on broker-dealers to prevent fat-finger orders and unmonitored market access.
- Minimum Order Rest Times and Order-to-Trade Ratios: Rules enforced by European regulators under MiFID II charging higher access fees to high-frequency traders displaying high order-cancellation rates relative to executed fills.
- Systems Integrity and Resilience Regulations (SEC Regulation SCI): Mandates that key exchanges, clearing agencies, and alternative trading systems maintain redundant infrastructure and disaster-recovery protocols.
Abusive Trading Practices and Real-Time Market Surveillance
The speed of electronic markets requires automated, real-time market surveillance by regulatory authorities—such as the US Financial Industry Regulatory Authority (FINRA), the US Securities and Exchange Commission (SEC), and the European Securities and Markets Authority (ESMA)—and exchange compliance divisions. Real-time monitoring algorithms detect manipulative market strategies, including:
- Spoofing: Submitting non-bona fide limit orders on one side of the order book with the intent to cancel them before execution. This creates a false impression of supply or demand, manipulating prices to benefit an opposing order.
- Layering: Placing multiple fake orders at varying price levels away from the best bid/ask, creating artificial depth and pushing the market quote in a targeted direction.
- Wash Trading: Simultaneously buying and selling the same financial instrument across accounts under common beneficial ownership to create artificial volume and fool market participants.
- Quote Stuffing: Flooding exchange matching engines with massive volumes of orders and rapid cancellations to generate processing latency for competitors.
- Front-Running and Momentum Ignition: Entering orders ahead of pending institutional trades or submitting aggressive orders to trigger stop-loss orders from other market participants.
Modern surveillance platforms deploy pattern-recognition algorithms, machine learning models, and cross-market data reconstruction to analyze order-book events, detecting microsecond manipulation anomalies.
Conclusion: Navigating Modern Market Microstructure
The interaction between trading costs and electronic markets defines performance outcomes across modern capital markets. Transaction costs—spanning explicit commissions and implicit frictions like market impact, delay, and opportunity cost—remain a primary determinant of net investment performance. Institutional asset managers must continuously refine their Transaction Cost Analysis (TCA) tools, leveraging metrics like effective spreads, VWAP benchmarks, and Implementation Shortfall models to evaluate execution quality.
Concurrently, market structure continues to evolve as electronic execution systems, market fragmentation, low-latency technologies, and algorithmic strategies reshape liquidity dynamics. Navigating this landscape requires balancing execution speed against price impact, leveraging smart order routing technology, maintaining compliance with pre-trade risk controls, and adhering to regulatory standards. Market participants who understand these market microstructure mechanics are better positioned to reduce execution drag, safeguard portfolio returns, and operate within global electronic markets.

