You don’t just buy a stock based on its current price, do you? Wise investors know that a company’s market price can be influenced by all sorts of things, from market sentiment to temporary news cycles. The real question is: Is the stock’s price reflective of its actual worth? This comprehensive business article explores the essential principles, advanced models, and real-world applications of equity valuation to help investors navigate global markets effectively.
Equity valuation is the foundational process of determining the intrinsic value of a company’s stock—what it is truly worth based on its operational and financial fundamentals, rather than just its current market trading price. By understanding a stock’s intrinsic value, investors and market analysts can determine whether a security is undervalued, overvalued, or fairly priced. This disciplined approach serves as the cornerstone of successful, long-term value investing, empowering stakeholders at corporations like Apple and Microsoft to make rational capital allocation decisions.
Introduction to Equity Valuation in Modern Markets
In today’s fast-paced financial ecosystem, market prices fluctuate constantly due to macroeconomic shifts, geopolitical events, and behavioral biases. However, price and value are distinct concepts. As legendary investor Warren Buffett famously noted, price is what you pay, and value is what you get.
Valuation bridges the gap between financial statements and investment decisions. Whether evaluating a mature manufacturing conglomerate or a high-growth technology startup, financial analysts rely on a diverse toolkit of quantitative models. These models are generally categorized into absolute valuation, relative valuation, and asset-based valuation methods. Each approach offers a unique lens through which to examine a company’s underlying financial health and future earnings potential.
Absolute Valuation Models
Absolute valuation models, also known as intrinsic valuation frameworks, attempt to determine a company’s standalone value without benchmarking it directly against competitor multiples. These models operate on the core economic principle that the true economic value of any financial asset equals the present value of all future cash flows it is expected to generate.
Discounted Cash Flow Model
The Discounted Cash Flow (DCF) model is widely regarded as the most rigorous and comprehensive absolute valuation method. The DCF model projects a company’s future free cash flows—the cash a business generates from its core operations after accounting for capital expenditures—and discounts them back to their present value using a discount rate that reflects the inherent risk of the investment.
The discount rate typically employed is the Weighted Average Cost of Capital (WACC). A stock is considered undervalued if its calculated DCF intrinsic value exceeds its current market trading price.
Mathematical Formulation of the DCF Model
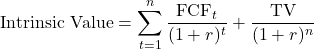

Where:


Practical DCF Calculation Example
Consider a hypothetical valuation of “Tech Innovations Inc.” with a WACC of 10 percent (


Step 1: Project Future Cash Flows
- Year 1 FCF: USD100 million
- Year 2 FCF: USD110 million
- Year 3 FCF: USD125 million
- Year 4 FCF: USD140 million
- Year 5 FCF: USD155 million
Step 2: Calculate the Present Value of Each Cash Flow


Step 3: Calculate the Terminal Value
The terminal value captures the value of all cash flows beyond the five-year projection period, calculated using the Gordon Growth Model:


Step 4: Calculate the Present Value of the Terminal Value


Step 5: Determine Total Intrinsic Value and Per Share Value


If Tech Innovations Inc. has 100 million shares outstanding, its intrinsic value per share is:


If the current market price is USD15.00, the stock is theoretically undervalued by the market.
Dividend Discount Model
The Dividend Discount Model (DDM) is a specialized variant of the absolute valuation framework. Instead of focusing on enterprise free cash flows, the DDM isolates the cash returned directly to shareholders via dividends.
This model is most suitable for stable, mature companies with predictable cash distribution histories, such as global utility providers or consumer staple giants like Procter & Gamble. The Gordon Growth Model represents the most common formulation of the DDM.
DDM Mathematical Formula


Where:


Practical DDM Calculation Example
Consider “Steady Dividends Corp.” Its most recent annual dividend was USD2.00 per share, expected to grow at a constant 4 percent per year (


Under this model, the intrinsic value of Steady Dividends Corp. is established at USD52.00 per share.
Relative Valuation Models
While absolute models provide theoretical intrinsic values, relative valuation models benchmark a target company against its industry peers. This methodology relies on market multiples and ratios, operating under the financial assumption that similar companies should trade at comparable valuation metrics.
Comparable Company Analysis
Comparable Company Analysis (Comps) is a primary tool utilized by financial institutions worldwide. Analysts select a peer group of publicly traded entities sharing similar business models, geographical exposure, and operational scale. Key valuation multiples—such as the Price-to-Earnings (P/E) ratio, Price-to-Sales (P/S) ratio, and Price-to-Book (P/B) ratio—are then evaluated to determine relative mispricing.
- Price-to-Earnings Ratio: Compares a company’s share price to its earnings per share, indicating how much investors are willing to pay for every dollar of corporate earnings.
- Price-to-Sales Ratio: Compares market capitalization to total sales revenue, frequently applied to early-stage technology enterprises lacking positive net income.
- Price-to-Book Ratio: Compares market value to accounting book value, commonly utilized in banking and capital-intensive sectors.
Practical Comps Calculation Example
Consider valuing “Future Tech Inc.” (FTI), a software enterprise with an annual net income of USD50 million. Three comparable industry competitors have been selected for benchmarking:
| Company | Market Capitalization | Net Income | P/E Ratio |
| FTI (Target) | Unspecified | USD50M | Unspecified |
| Competitor A | USD1.2B | USD60M |  |
| Competitor B | USD2.0B | USD80M |  |
| Competitor C | USD1.5B | USD75M | |


Step 1: Calculate Peer Average P/E Ratio


Step 2: Apply Multiple to Target Earnings


The relative valuation of Future Tech Inc. amounts to approximately USD1.08 billion.
Precedent Transaction Analysis
Precedent Transaction Analysis values a target company by examining historical acquisition prices paid for similar corporate entities in past mergers and acquisitions (M&A). This approach incorporates control premiums and is heavily utilized in corporate finance advisory to gauge acquisition value.
Practical Transaction Example
Suppose an industry peer of Future Tech Inc. was acquired at a multiple of


Asset-Based Valuation Models
Asset-based valuation approaches focus on balance sheet fundamentals rather than future cash flows or earnings multiples. This methodology is particularly valuable for distressed companies or capital-intensive enterprises with significant tangible assets.
Liquidation Value Analysis
Liquidation value determines the net cash amount a company would generate if its operations ceased immediately and all assets were sold off independently after settling outstanding obligations. This metric serves as an absolute valuation “floor” for an enterprise.
Practical Liquidation Value Calculation Example
Consider “Widgets Inc.,” a manufacturing enterprise with the following balance sheet summary:
- Tangible Assets:
- Cash and Cash Equivalents: USD50 million
- Inventory (Liquidation Basis): USD30 million
- Plant, Property & Equipment (Liquidation Basis): USD120 million

- Liabilities:
- Accounts Payable: USD20 million
- Long-Term Debt: USD80 million


Calculation:


The liquidation value establishes a minimum valuation floor of USD100 million for shareholders in the event of an orderly corporate wind-down.
Conclusions and Strategic Insights
Equity valuation is both an analytical science and a practical art form. No single valuation model is universally flawless; each methodology carries unique operational strengths and structural limitations.
Savvy investors, financial analysts, and corporate leaders combine absolute frameworks like DCF with relative peer benchmarks to construct a comprehensive valuation range. By looking past daily stock market volatility and anchoring decisions in rigorous intrinsic analysis, market participants can identify compelling investment opportunities and achieve long-term financial success.

